Restaurant & Café Insurance Quote For Your Business
Restaurant & Café Insurance Coverage in Ontario
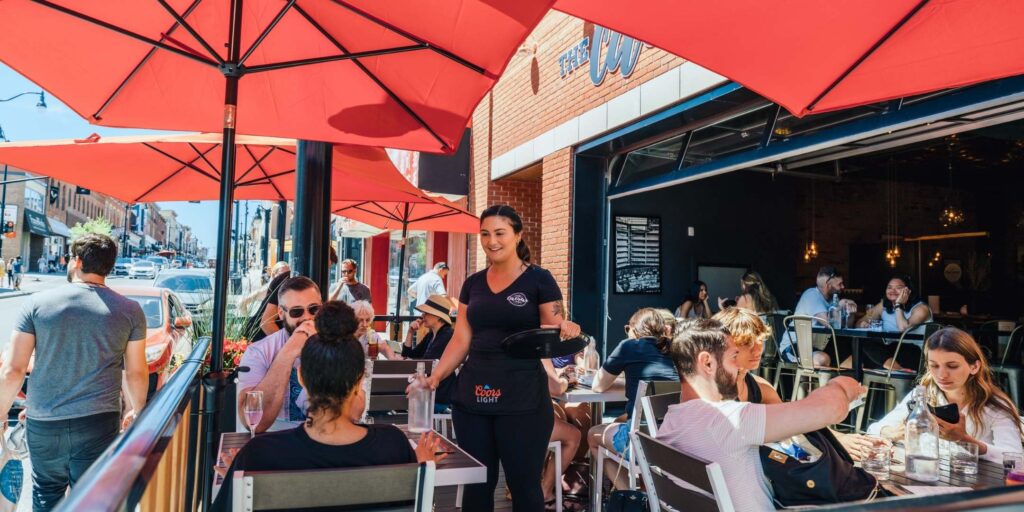
Operating a restaurant in Canada involves more than serving great food. From kitchen fires and equipment failures to customer injuries, food contamination, and unexpected business interruptions, restaurant owners face a wide range of risks that can affect their operations and profitability. Even a single incident can result in significant financial losses, legal expenses, or prolonged downtime.
Restaurant insurance is designed to help protect your business from these unexpected events by providing financial support for covered property damage, liability claims, lost income, equipment breakdowns, and other operational risks. With the right coverage in place, restaurant owners can focus on delivering exceptional customer experiences with greater confidence and peace of mind.
We understand that your vehicle is essential to your livelihood. That is why we focus on delivering insurance protection designed specifically for the unique needs of the taxi industry.
Mandatory
Commercial General Liability (CGL)
Protects your restaurant against third-party claims for bodily injury, property damage, and legal expenses arising from your business operations.
While not legally required in most provinces, many commercial landlords, lenders, and franchise agreements require restaurants to carry $2 million to $5 million in Commercial General Liability coverage before signing a lease or contract.
Example: A customer slips on a wet floor and suffers an injury. CGL insurance can help cover legal defence costs, settlements, and other covered expenses related to the claim.
Commercial Property Insurance (often required by landlords and lenders)
Commercial Property Insurance helps protect your restaurant’s physical assets, including the building (if owned), kitchen equipment, furniture, inventory, and supplies, against covered losses such as fire, theft, vandalism, and certain types of accidental damage.
Example: A kitchen fire damages ovens, refrigeration units, and restaurant furniture. Commercial Property Insurance can help cover the cost of repairing or replacing the damaged property and equipment, helping your restaurant resume operations more quickly.
Liquor Liability Insurance (required if serving alcohol and depending on provincial licensing requirements)
Liquor Liability Insurance helps protect your restaurant against claims arising from the sale or service of alcohol, including incidents involving intoxicated customers.
While liquor liability requirements vary by province and insurer, restaurants that serve alcohol should consider this coverage to help protect against potentially significant legal and financial exposures.
Example: A customer leaves your restaurant after consuming alcohol and is involved in an accident. Liquor Liability Insurance may help respond to covered claims alleging the restaurant contributed to the incident, subject to the policy’s terms, conditions, and limits.
Mandatory
Commercial General Liability (CGL)
Protects your restaurant against third-party claims for bodily injury, property damage, and legal expenses arising from your business operations.
While not legally required in most provinces, many commercial landlords, lenders, and franchise agreements require restaurants to carry $2 million to $5 million in Commercial General Liability coverage before signing a lease or contract.
Example: A customer slips on a wet floor and suffers an injury. CGL insurance can help cover legal defence costs, settlements, and other covered expenses related to the claim.
Commercial Property Insurance (often required by landlords and lenders)
Commercial Property Insurance helps protect your restaurant’s physical assets, including the building (if owned), kitchen equipment, furniture, inventory, and supplies, against covered losses such as fire, theft, vandalism, and certain types of accidental damage.
Example: A kitchen fire damages ovens, refrigeration units, and restaurant furniture. Commercial Property Insurance can help cover the cost of repairing or replacing the damaged property and equipment, helping your restaurant resume operations more quickly.
Liquor Liability Insurance (required if serving alcohol and depending on provincial licensing requirements)
Liquor Liability Insurance helps protect your restaurant against claims arising from the sale or service of alcohol, including incidents involving intoxicated customers.
While liquor liability requirements vary by province and insurer, restaurants that serve alcohol should consider this coverage to help protect against potentially significant legal and financial exposures.
Example: A customer leaves your restaurant after consuming alcohol and is involved in an accident. Liquor Liability Insurance may help respond to covered claims alleging the restaurant contributed to the incident, subject to the policy’s terms, conditions, and limits.
Through our partnership with Goodrates Insurance, we offer some of the most comprehensive taxi insurance plans available. In addition to protecting your vehicle, our coverage can include:
Loss of income protection following a covered claim
Roadside assistance expenses
Coverage for passengers' personal belongings
Third-party liability protection
Additional coverage options tailored to your business needs
Speak with our BD Team Today
Speak with our BD Team Today
Our knowledgeable BD Team are committed to understanding your specific requirements. We will conduct a thorough assessment of your operation and recommend the insurance solution that best protects your business, your vehicle, and your income.
Contact Goodrates Insurance today to receive expert advice and a customized taxi insurance quote.
Switching insurance has never been this easy
Step 1
Fill out the form at the top of the page.
Step 2
A 15-min meeting will be scheduled with our advisors.